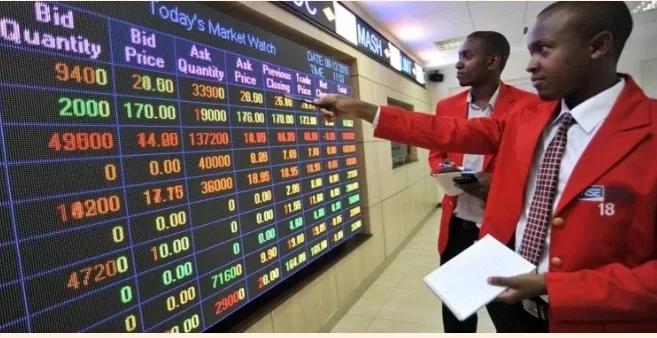
Kenya's Capital Markets Tribunal has been unable to hear and determine appeals for nearly five months because it lacks the required quorum, leaving corporate disputes and challenges to regulatory decisions unresolved at a time the country is trying to deepen its capital markets and attract more investment.
The specialised tribunal has reportedly been unable to sit since mid-May 2026 following vacancies created by the departure of key members.
Its former chairperson, Paul Lilan, was appointed a judge of the Court of Appeal in January, while other members' terms subsequently expired.
The Judicial Service Commission advertised vacancies for a chairperson and two non-advocate members in July, with applications closing on August 13, but the appointments had not been completed by the time the paralysis was reported this week.
The result is an institutional bottleneck affecting companies and investors seeking to challenge decisions made by the Capital Markets Authority.
What does the Tribunal do?
The Capital Markets Tribunal provides a specialised appeals mechanism for disputes arising from Kenya's capital-markets regulatory system.
Under the Capital Markets Act, a person aggrieved by certain actions or decisions of the Capital Markets Authority or Investor Compensation Fund Board can appeal to the Tribunal.
The law allows the Tribunal to require the regulator to justify its action and either affirm or set aside the disputed decision after hearing the parties.
Its jurisdiction matters because capital-market disputes can involve substantial sums, listed companies, investment funds, directors and regulatory sanctions.
The alternative of pushing every dispute into the ordinary court system can result in longer proceedings and can shift cases away from a specialised forum designed to understand securities regulation and market conduct.
High-value disputes caught in uncertainty
The lack of quorum has reportedly left several corporate disputes and regulatory appeals in limbo.
One example involves the long-running proposed acquisition of BOC Kenya by Carbacid Investments.
The transaction has faced a challenge from a minority shareholder who disputes aspects of the proposed takeover.
The Capital Markets Authority has acknowledged that the Tribunal has not been able to hear the matter because it is not quorate.
The wider problem is not simply whether one takeover proceeds.
When companies or investors disagree with regulatory decisions, they need to know where their appeals can be heard and how long a determination is likely to take.
Uncertainty has a financial cost.
Transactions can be delayed, capital can remain tied up and companies may be unable to make decisions while waiting for regulatory disputes to be resolved.
Tribunal only returned in 2023
The current paralysis is particularly notable because the Tribunal was reconstituted only in June 2023 after years of inactivity.
Since returning, it had begun building a body of decisions dealing with corporate governance, board responsibility and conduct in Kenya's securities markets.
The High Court has also recognised the Tribunal's role as the appropriate forum for some capital-market disputes.
In a July 2026 ruling involving NCBA Investment Bank, the High Court struck out a case after finding that the dispute should have been taken through the mechanism provided for determination by the Capital Markets Tribunal.
That creates an obvious problem if parties are directed towards a specialist tribunal that is simultaneously unable to sit.
Investor confidence is about institutions too
Kenya has been aggressively pitching itself as an investment destination.
President William Ruto's administration wants more companies to raise money through the Nairobi Securities Exchange, increase foreign investment and deepen domestic capital markets.
Those ambitions require more than investment conferences and incentives.
Investors also need functioning institutions.
An investor must be confident that if a regulator imposes a sanction or blocks a transaction, there is an accessible mechanism for challenging that decision.
The Tribunal does not exist to automatically side with investors against the CMA.
Its role is to provide an independent process through which regulatory disputes can be heard and determined.
That process also benefits the regulator because decisions can clarify the interpretation of securities law and reinforce legitimate enforcement action.
Five months is significant
Administrative vacancies occur in public institutions.
But allowing a key financial-market appeals body to remain unable to hear cases for months creates a broader governance question.
Capital markets operate on confidence.
Investors price uncertainty, and institutional delays can become part of that calculation.
The JSC recruitment process therefore has implications beyond filling vacant public positions.
Restoring the Tribunal's quorum would reopen an important part of Kenya's investor-protection and regulatory architecture.
Kenya wants businesses and individuals to put more money into its capital markets.
Those investors are entitled to expect that when disputes arise, the institutions created to resolve them are actually capable of sitting.
You may also like
Category: Business
Related Video: Beyond Aid: How Japan Is Shaping Kenya’s SME Future | JICA Training Experience
Related Explainer: EXPLAINER: How can one mother give birth to five babies? The science behind Kenya’s rare quintuplets
 Facebook
 Twitter / X
 WhatsApp
 LinkedIn
 Telegram
 Reddit