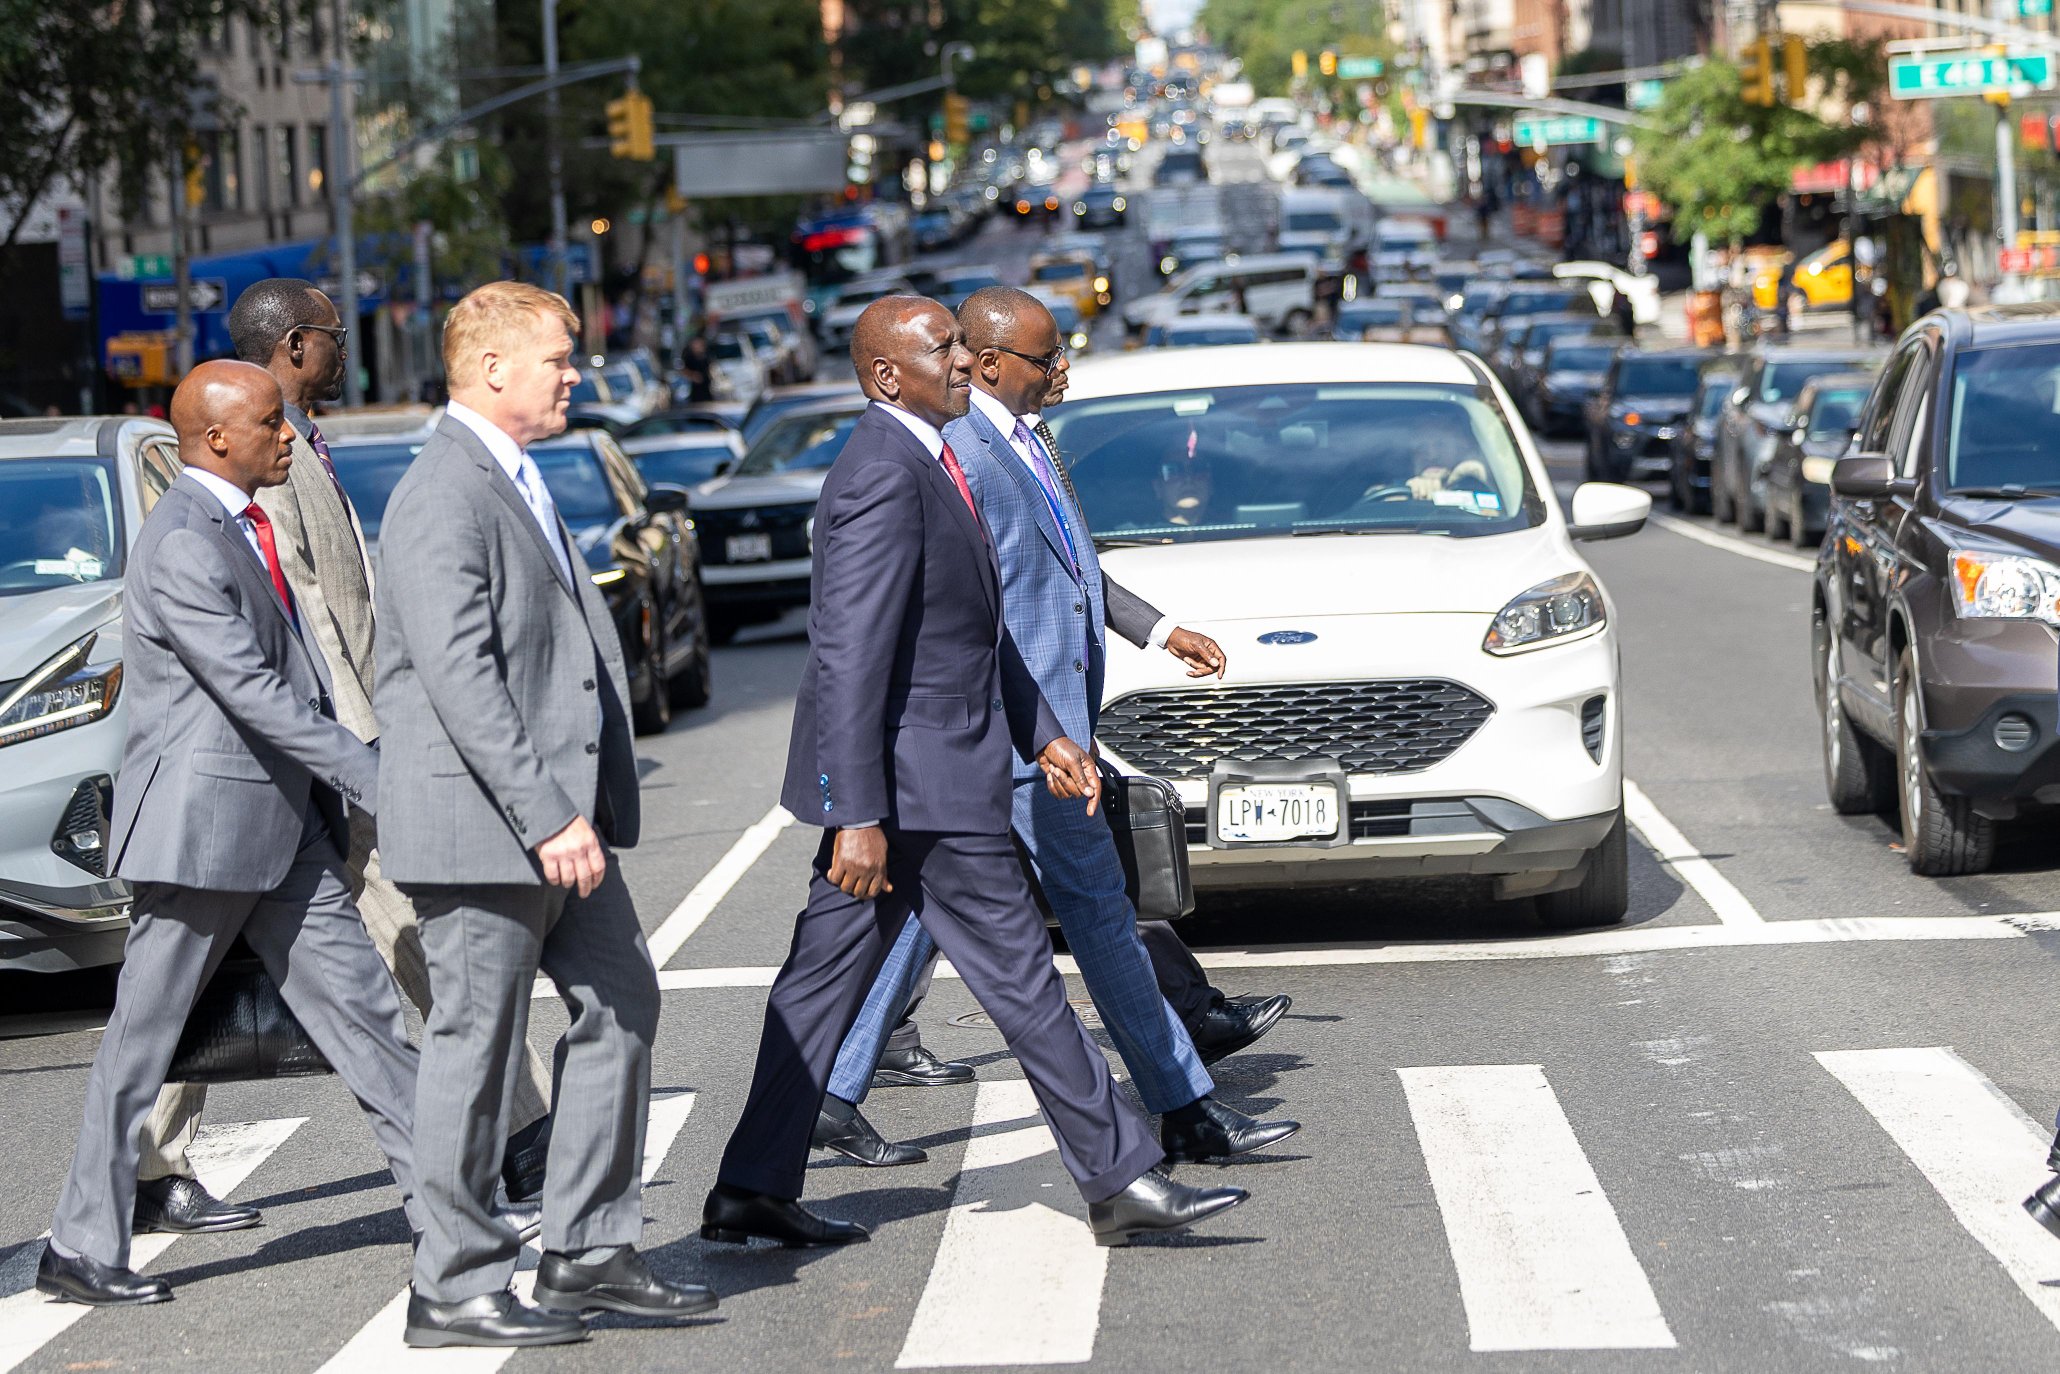
President William Ruto has become an increasingly forceful advocate for Africa on the world stage. In New York, Washington and other global forums, he speaks the language of structural reform: cheaper capital for Africa, a permanent African voice at the United Nations Security Council, climate justice, investment instead of dependency, industrialisation instead of extraction and a global financial architecture that treats developing countries more fairly.
His address to the 81st United Nations General Assembly this week was a particularly polished expression of that argument. Ruto told world leaders that Africa was not approaching the international community with a begging bowl.
“Africa does not come to plead. We come with a proposal,” he said, before setting out the continent's mineral wealth, agricultural potential, renewable-energy resources and young population as assets capable of driving global growth.
It is an argument with substance.
But a social-media intervention by Doanh Chau, reacting to coverage of Ruto's speech, identified the uncomfortable question that follows the applause.
“Yes, the message is powerful,” Chau wrote in the post shared with this article. “Powerful enough to tell the international audience: Kenya is ready, please invest more.”
He then asked what happens after potential investors leave the conference hall.
“Is the electricity reliable? Are the roads there? Are contracts enforceable? Is procurement transparent? Can capital trust the institutions?”
His conclusion was sharper still: “That is where a powerful speech meets reality.”
That observation deserves attention because it goes to the heart of the Ruto presidency's international economic strategy.
The problem is not that the President's global argument is necessarily wrong. Much of his critique of the international financial system is supported by evidence.
The problem is that Kenya must simultaneously demonstrate that the reforms it demands internationally are being pursued domestically.
And that is where rhetoric encounters a much more complicated record.
Ruto is right about expensive capital
Take one of the strongest arguments in his UN address.
Ruto said developing countries often borrow at rates two to four times higher than developed economies and cited UNDP estimates that subjectivity in sovereign credit ratings has cost African countries about $75 billion through excessive interest and foregone lending.
“Capital must price risk. It must not price prejudice,” he said.
His broader argument — that African countries face disproportionately high financing costs — is well established in international development debates.
But an investor considering Kenya does not assess only whether the global system is fair.
They also assess Kenya itself.
And Kenya still carries significant fiscal risk.
The World Bank says public debt is about 70.6 per cent of GDP, with roughly one-third of government revenues absorbed by interest payments. It assesses Kenya as being at high risk of debt distress.
That distinction matters.
Some of Africa's borrowing premium may reflect structural biases in international finance. But some of Kenya's borrowing cost reflects real domestic fiscal vulnerabilities.
Ruto himself acknowledged this in New York.
“Governments must also do their part to manage debt prudently, strengthen institutions, prepare pipelines of credible projects, deepen domestic capital markets, honour contracts and confront corruption without equivocation,” he said.
Then came perhaps the most important sentence of his entire address:
“Reform abroad cannot substitute for accountability at home.”
That line could become the standard against which his own government is measured.
Borrowing to pay today's bills
Consider Kenya's public finances.
Treasury documents reported in August showed that the government borrowed Sh983.7 billion during the 2025/26 financial year, but only Sh776 billion went into development expenditure.
That means about Sh207.7 billion of borrowed money financed recurrent expenditure, including salaries and debt repayments, rather than long-term assets such as roads, schools, hospitals or dams.
There is an obvious tension here.
On the global stage, Kenya argues that expensive capital prevents developing countries from building infrastructure.
At home, some borrowed capital is not building infrastructure at all.
The government also failed for the fourth consecutive year to meet the legal requirement that at least 30 per cent of ministerial expenditure go towards development.
Development expenditure accounted for 26.89 per cent, leaving spending roughly Sh85 billion short of the statutory threshold.
None of this invalidates Ruto's argument for reform of international finance.
It does, however, strengthen Chau's central point: attracting capital and using capital productively are different problems.
The roads tell their own story
Infrastructure provides another example.
Kenya has an impressive network of major highways compared with many countries in the region, and infrastructure remains central to the government's investment pitch.
But contractors have also spent years waiting for government payments.
In April, the government released another Sh20 billion to road contractors as part of an effort to clear pending bills. That brought payments to contractors since April 2025 to Sh202 billion. Some contractors had faced severe cash-flow difficulties and even possible auctions by lenders while waiting for government payments.
Then there is the Rironi-Mau Summit highway.
The previous public-private partnership with French firms was abandoned after the Treasury concluded that a structure involving about Sh299 billion in service fees over 13 years was financially untenable. The project was subsequently shifted to a different financing and construction arrangement.
Infrastructure ambition is not Kenya's problem.
Execution, financing discipline and contractual certainty often are.
Electricity: connected does not always mean reliable
Chau's first question was particularly practical:
“Is the electricity reliable?”
Kenya has made substantial progress expanding electricity access and has an unusually renewable-heavy generation mix.
But connection and reliability are not the same thing.
A World Bank assessment of Kenyan enterprises found that 97 per cent of businesses surveyed were electrified, yet the quality of supply remained a significant bottleneck. Only about half reached the highest Tier 5 level of electricity access, dropping to fewer than one-third among informal enterprises.
For a household, an outage is an inconvenience.
For a factory, data centre, hospital or other electricity-intensive investment, reliability is part of the business model.
An investor deciding where to locate a manufacturing plant calculates the cost of backup generation, downtime and equipment disruption alongside wages and taxes.
That calculation cannot be improved by rhetoric.
It requires transformers, transmission lines, reserve capacity, maintenance and competent utility management.
Then comes the uncomfortable word: corruption
Ruto's UN speech explicitly said governments must “confront corruption without equivocation.”
Kenya's record remains difficult.
Transparency International's latest country data gives Kenya a score of 30 out of 100 on the Corruption Perceptions Index, ranking it 130th out of 182 countries. Transparency.org
The index measures perceptions of public-sector corruption rather than proving corruption in individual transactions. But for an investor, perception itself has economic consequences.
A company considering a multimillion-dollar factory wants to know whether licences can be obtained predictably, procurement is competitive, contracts are enforceable and disputes can be resolved without political connections.
These are not moral questions alone.
They affect the price of capital.
The irony is striking: Kenya rightly complains that international markets sometimes exaggerate African risk, but weak domestic institutions can simultaneously create genuine risk.
The World Bank itself has made the connection explicit.
When it approved a $750 million development policy operation for Kenya in June, it said governance and public-finance reforms were important to establishing the regulatory certainty required to attract private investment and create jobs.
In other words, institutional credibility is economic infrastructure.
The accountability contradiction
The contrast becomes even sharper when Ruto speaks internationally about accountable institutions.
During his New York meetings this week, the President said Kenya supports an open society in which citizens freely participate in public affairs and institutions remain accountable.
Yet the Kenya National Commission on Human Rights documented serious allegations arising from the June 25, 2026 protests.
The constitutional commission reported seven incidents of enforced disappearance, widespread arrests and allegations of torture, unlawful use of force and violations of media freedom. It documented 361 arrests across several counties and said some officers deployed during demonstrations were hooded, in plain clothes or operating from unmarked vehicles despite court requirements on police identification.
Those findings cannot simply be collapsed into an accusation that the President personally directed violations. They require investigation and accountability through the appropriate institutions.
But they illustrate the credibility problem.
A country cannot separate its international governance brand from what its citizens experience at home.
Investors also observe the rule of law, institutional independence and social stability.
The macroeconomy has improved — but households tell another story
It would be unfair to describe Ruto's economic story as entirely rhetorical.
There are measurable improvements.
The World Bank describes Kenya's macroeconomic framework as “broadly stable”, supported by resilient growth, low core inflation and stronger external buffers. It forecasts economic growth of about 4.6 per cent in 2026.
Ruto has also cited a stable shilling, growing foreign-exchange reserves and lower borrowing costs as evidence that confidence has returned.
These gains matter.
But macroeconomic stability is not synonymous with household prosperity.
The same World Bank assessment says formal jobs account for only about 16.2 per cent of employment, while poverty at the $3-a-day international line was about 43.3 per cent in 2025 and is projected to decline only marginally to around 43 per cent in 2026.
Another recent policy assessment noted that between 800,000 and one million young Kenyans enter the labour market annually, while the formal economy generated only 78,600 jobs in 2024. More than 80 per cent of employed young people were working in the informal economy.
This is where national statistics collide with lived experience.
A stronger shilling matters.
Foreign-exchange reserves matter.
GDP growth matters.
But the young graduate who cannot find stable employment measures the economy differently.
And this is the real test of the Lamu refinery
Ruto's UN address contained a spectacular example of his investment vision.
He announced that Kenya expects to break ground on the planned East Africa refinery in Lamu, describing a project of approximately $16 billion capable of processing 700,000 barrels of oil per day.
He presented it as evidence of a new African development model: process resources locally, create jobs and build industries rather than export raw commodities.
Conceptually, it fits his argument perfectly.
But this is precisely the kind of project where Chau's questions become relevant.
Where will 700,000 barrels of crude per day come from?
Who will provide the billions of dollars required?
What guarantees will investors receive?
What infrastructure must be built around Lamu?
How will environmental and community concerns be managed?
What portion of the financing risk ultimately sits with taxpayers?
And can the project produce refined fuel competitively?
A groundbreaking ceremony answers none of those questions.
Execution does.
Kenya does not need fewer big ideas
There is a danger in responding to ambitious political rhetoric with reflexive cynicism.
Kenya needs leaders who can sell the country internationally.
Presidents are supposed to attract investment.
Africa does have legitimate grievances about representation in global institutions.
The international financial architecture does disadvantage many developing countries.
Africa should process more of its minerals and agricultural products locally.
Kenya should compete for global capital.
Those arguments deserve to be made.
Ruto is often effective at making them.
The more important question is what happens when the microphone is switched off.
That is why Chau's final challenge cuts deeper than a routine criticism of another presidential speech:
“Before asking the world for another dollar, perhaps the more important question is: What happened to the dollars already invested?”
That question should not be interpreted as an argument against investment.
It is an argument for credibility.
Investors do not ultimately invest in speeches. They invest in power systems that work, roads that reach markets, contracts that survive changes of government, courts that resolve disputes, procurement systems they can trust, skilled workers they can hire and institutions that behave predictably.
Ruto understands this at least rhetorically. His own UN address acknowledged that international reform cannot replace accountability at home.
The challenge for his administration is therefore unusually clear.
Kenya's President has become adept at explaining to the world what is wrong with the global system.
His harder assignment is demonstrating that Kenya can fix what is within Kenya's own control.
Until the distance between those two realities narrows, the President's speeches may continue moving audiences abroad while leaving many Kenyans at home asking a less glamorous question:
When does the rhetoric become reality?
You may also like
Category: Opinion · Related Topic: William Ruto
Related Video: Murkomen Says Kenya Is Safe: “Stop Creating a Crisis” | Political Goons & Security Under Scrutiny
Related Explainer: Kenya G-to-G Oil Deal Explained: How It Works, Who Supplies the Fuel and Why It Is Controversial
 Facebook
 Twitter / X
 WhatsApp
 LinkedIn
 Telegram
 Reddit