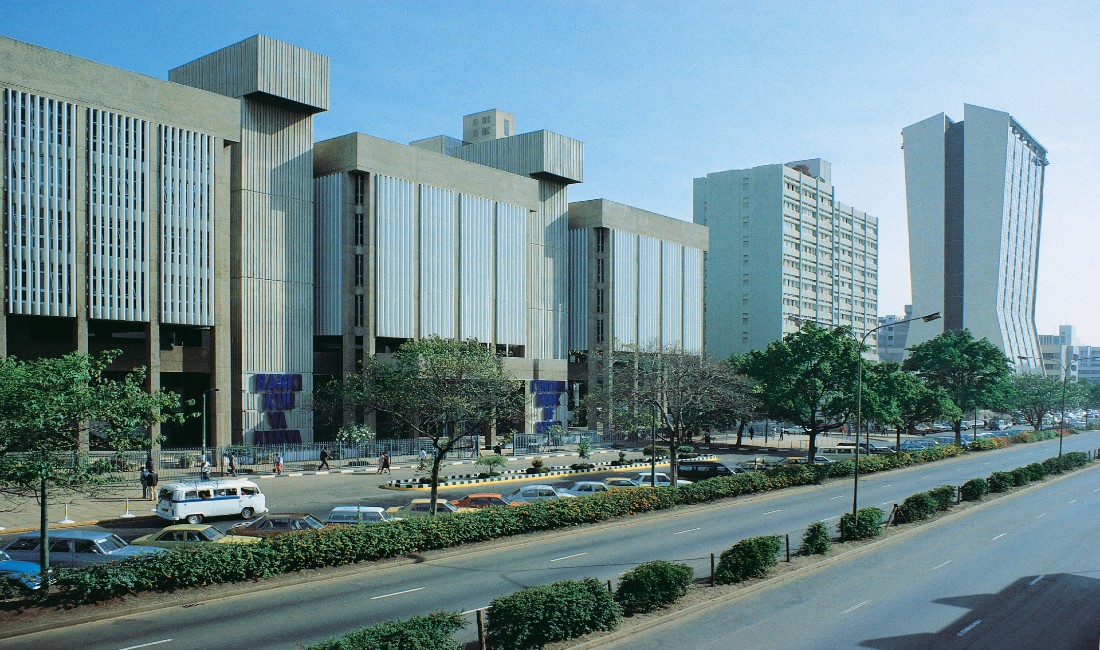
The Central Bank of Kenya has penalised a record 33 commercial banks after inspections found widespread failure to adjust lending rates in line with reductions in the benchmark Central Bank Rate, putting fresh pressure on lenders over the cost of credit to households and businesses.
The enforcement action affects 33 of Kenya's 38 commercial banks, representing nearly 87 per cent of the industry. CBK also took administrative action against another two banks, leaving only three institutions fully compliant with the regulator's risk-based credit pricing requirements.
The findings are significant because the Central Bank has repeatedly reduced its benchmark rate in an attempt to make borrowing cheaper and stimulate economic activity.
Between August 2024 and August 2025, CBK reduced the Central Bank Rate seven times, taking it from 13 per cent to 9.5 per cent. But the reductions have not always been transmitted to borrowers at the same speed.
For someone servicing a mortgage, business loan or personal loan, that gap matters. A reduction in the benchmark rate is intended to lower banks' funding and lending costs, but customers receive little immediate benefit if commercial lending rates remain elevated.
The regulator has not publicly identified the 33 banks or disclosed the individual penalties imposed. That leaves borrowers unable to determine whether their own lender was among those found in breach.
The controversy also exposes a recurring problem in monetary policy. CBK can reduce its policy rate, but the economic benefit depends partly on commercial banks passing lower rates through to borrowers.
Banks, meanwhile, price loans according to several factors beyond the benchmark rate, including the perceived risk of the customer, operating costs and the likelihood of default.
The enforcement action therefore does not mean every borrower should expect an identical reduction.
It does, however, signal that CBK believes the industry's response to monetary easing has been inadequate.
The development comes as many Kenyan households and businesses continue to complain about the high cost of credit despite falling benchmark rates.
For small businesses, expensive borrowing can delay expansion, hiring and investment. For households, it can mean larger monthly repayments and less disposable income.
The next question is whether enforcement will produce measurable reductions in lending rates.
Borrowers should watch their banks' base rates, risk premiums and loan statements rather than assuming a CBK rate cut automatically translates into cheaper credit.
The episode will also increase pressure on the regulator to disclose more information about compliance across the banking sector.
If almost nine out of every ten commercial banks required enforcement action, the larger policy question is why transmission of lower rates has proved so difficult — and what CBK will do if lenders continue resisting.
The regulator's intervention makes this more than a banking-industry story. It is ultimately about whether Kenya's monetary policy is reaching the households and businesses it is designed to support.
You may also like
Category: Business
Related Video: Murkomen Says Kenya Is Safe: “Stop Creating a Crisis” | Political Goons & Security Under Scrutiny
Related Explainer: Fact Check: Did elephants save people during Nepal’s floods?
 Facebook
 Twitter / X
 WhatsApp
 LinkedIn
 Telegram
 Reddit