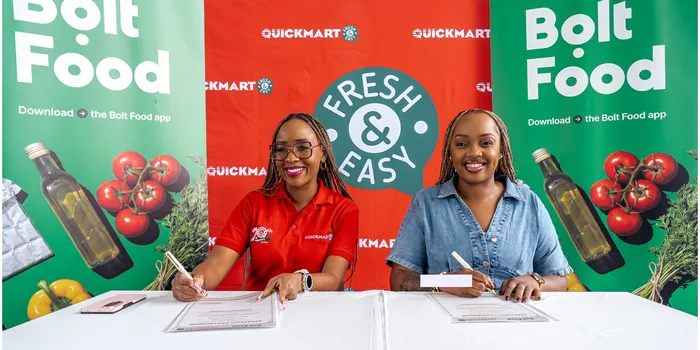
Quickmart has revealed an unusual feature of the financing model behind one of Kenya's biggest supermarket chains: suppliers, rather than banks, provide much of the working capital that keeps its shelves stocked.
The retailer, which is preparing for a listing on the Nairobi Securities Exchange, records annual sales exceeding Sh50 billion but had borrowings of only Sh6.8 million at the end of June 2026.
At the same time, it owed suppliers approximately Sh4 billion.
That contrast provides an insight into how large retailers can finance rapid growth without taking conventional bank loans.
Suppliers deliver products to Quickmart stores and receive payment later. Quickmart can therefore sell some of that inventory before it has to pay the businesses that supplied it.
The model is known as negative working capital and can be extremely efficient when a retailer turns over inventory quickly.
Quickmart says its Sh4 billion negative working-capital position reflects rapid inventory turnover and favourable supplier payment terms.
For investors considering buying shares when Quickmart comes to the NSE, the disclosure matters.
Low conventional borrowing can reduce interest expenses and protect profits when bank lending rates are high.
But supplier financing is not free of risk.
A retailer depends on suppliers continuing to accept delayed payment. If suppliers shorten payment periods, demand cash upfront or face their own financial difficulties, the retailer may suddenly require additional working capital.
The model therefore works best when a supermarket has significant bargaining power and predictable sales.
Quickmart's disclosure also highlights the growing sophistication of Kenya's retail market.
The sector has experienced spectacular corporate failures in the past, including supermarkets that expanded aggressively while accumulating obligations they could not ultimately meet.
That history means investors will pay particular attention to cash flow, supplier obligations, profitability and governance as Quickmart approaches the public market.
The company's NSE listing will also be significant for Kenya's capital markets.
The exchange has struggled for years to attract major new consumer-facing companies, even as private businesses have expanded across the economy.
A successful supermarket listing would give ordinary investors exposure to a business whose stores and products they encounter daily.
But familiarity with a brand is not the same as understanding its finances.
Potential shareholders will need to examine the company's prospectus, margins, store-expansion strategy, supplier concentration and cash-generation capacity before making investment decisions.
Quickmart's financing model is therefore one of the most revealing details to emerge ahead of its listing.
The supermarket has demonstrated that rapid retail growth does not necessarily require huge bank borrowing.
The challenge now is demonstrating that the supplier relationships supporting that growth are durable enough to work under the scrutiny of public-market investors.
Category: Business
Related Video: Beyond Aid: How Japan Is Shaping Kenya’s SME Future | JICA Training Experience
 Facebook
 Twitter / X
 WhatsApp
 LinkedIn
 Telegram
 Reddit